Key Takeaways:
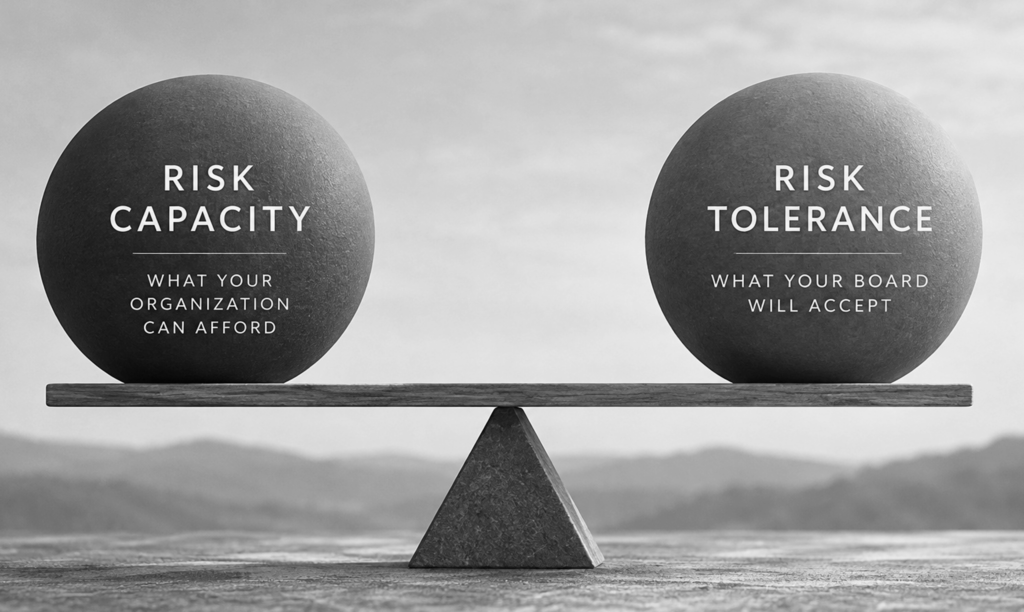
- Risk capacity is how much investment decline your organization can absorb without changing its programs, operations, or commitments; risk tolerance is how much decline your board will accept and still stay with the strategy.
- Risk capacity is typically assessed pool by pool, based on factors such as time horizon, restricted funds, any regular draw from the portfolio, revenue stability and concentration, and the depth of other reserve pools.
- Risk tolerance is typically assessed through a survey completed by each committee or board member, followed by a discussion of where the answers differ.
- When risk tolerance and risk capacity do not match, the portfolio for each pool is generally built to whichever supports less risk, and the gap is recorded for future review.
- Risk capacity shapes the reserve policy and each pool’s cash flow expectations and time horizon in the Investment Policy Statement, while risk tolerance is reflected in each pool’s risk level, allocation ranges, and eligible investments.
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment advice. Raffa Investment Advisers is a registered investment adviser. Each organization’s financial situation is unique. Please consult with a qualified investment professional before making financial decisions.
How Risk Tolerance and Risk Capacity Differ
The difference between risk tolerance and risk capacity is the difference between willingness and ability. Risk capacity is the amount of investment decline your organization can absorb without forcing a change in its programs, operations, or commitments. Risk tolerance is the amount of decline your board and finance committee are willing to accept without abandoning the investment strategy. When a finance committee disagrees about how much risk to take, separating the two can show whether the disagreement is about the organization’s finances or about members’ comfort with market declines.
This article covers how to assess your nonprofit’s risk capacity and your board’s risk tolerance, what to do when the two do not match, how the result is reflected in your reserve policy and Investment Policy Statement (IPS), and when to revisit it.
Risk Capacity vs. Risk Tolerance Compared
Side by side, risk capacity and risk tolerance differ in what they measure, what the board bases each on, and where each is typically reflected.
| Compared on | Risk capacity | Risk tolerance |
|---|---|---|
| What it measures | The decline the organization can absorb without changing programs, operations, or commitments | The decline the board will accept without abandoning the strategy |
| What the board bases it on | The organization’s financial position | Members’ own views on risk and market declines |
| What drives it | When each pool will be needed, restricted fund schedules, reliance on the portfolio, revenue stability, and the depth of other reserve pools | Members’ financial backgrounds, experience with past declines, comfort with short-term losses, and board and committee rotation |
| How it is assessed | Typically a review of financial statements, budgets, cash flows, the strategic plan, and the reserve policy, plus conversations with leadership, pool by pool | Typically a risk tolerance survey completed by each committee or board member |
| How often it changes | When reserves, revenue, spending, or plans change | When board or committee members rotate, after members experience a significant market decline, or as members become more familiar with how each pool is invested |
| Where it is typically reflected | Indirectly, through the reserve policy (which pools to hold, what each is for, and how much each should hold), carried into each pool’s cash flow expectations and time horizon in the IPS | Directly, in each pool’s section of the IPS: a risk level, such as conservative or moderate, allocation ranges, and limits on eligible investments |
What Is Risk Capacity for a Nonprofit?
Risk capacity for a nonprofit is the amount of investment decline the organization can absorb without having to cut programs, delay commitments, or sell investments to cover a shortfall.
The primary driver of capacity is when the money will be needed. Money that may be spent in the next year or two has little room for a decline, because there may be little time to recover before it is used, while money with no planned use for many years generally has more. Because each reserve pool has its own timing, capacity is typically assessed pool by pool, whether the pools are held in separate portfolios or tracked within a single portfolio.
Purpose matters as well. An emergency reserve may be needed during a market decline, so it generally has a lower capacity for risk and is invested more conservatively than a strategic reserve held for long-term growth, as our article on how emergency and strategic reserves differ in purpose and time horizon explains.
Capacity also depends on how much the operating budget relies on the portfolio. If the budget depends on a regular draw, a decline reduces next year’s funding as well as the balance. Revenue matters in a similar way: if revenue tends to fall in an economic downturn, as donations or dues from members of a single industry can, the organization is more likely to need its reserves at a time when markets may also be down. The spending schedules on restricted funds and the depth of other reserve pools also affect capacity.
How to Assess Your Nonprofit’s Risk Capacity
Your nonprofit’s risk capacity is typically assessed by reviewing the organization’s financial statements, budget, cash flows, strategic plan, and reserve policy, along with conversations with leadership about when funds are expected to be used. From there, the committee can consider how each of the factors below raises or lowers the risk capacity for each reserve pool. Note that the factors below are intended to aid the discussion, but are not necessarily a complete list or a formula that produces an allocation.
Factors That Raise or Lower Risk Capacity
When reviewing each reserve pool, it can be helpful to consider whether the following factors tend to raise or lower its risk capacity. Where several factors point toward lower capacity, a more conservative approach may be worth discussing.
| Factor | Tends to raise capacity | Tends to lower capacity |
|---|---|---|
| Time horizon of the pool | No planned use for five years or more | Expected to be spent within one to three years |
| Restricted funds | Unrestricted money, or restricted money with a long time horizon | Restricted money that must be spent on a set schedule in the near term |
| Draw from the portfolio | A small draw relative to the portfolio size or a set annual spending amount | Large, irregular spending needs |
| Revenue stability | Revenue is predictable and has generally held up in past economic downturns | Revenue varies widely or tends to fall in a downturn, when markets may also be down |
| Revenue concentration | Revenue comes from several independent sources | A large share comes from one source, such as a single funder, grant, or conference |
| Depth of other reserve pools | Other reserves, such as operating and emergency reserves, can cover a shortfall before this pool is needed | Few other reserves stand ahead of this pool, so it may be needed to cover a shortfall |
What Is Risk Tolerance for a Nonprofit Board?
Risk tolerance for a nonprofit board is the amount of short-term decline the board and its finance committee are willing to accept in pursuit of long-term results. The National Council of Nonprofits advises that before a nonprofit invests, the board should develop its approach to investing by defining its objectives, identifying the nonprofit’s risk tolerance (not your personal risk tolerance), and adopting an investment policy statement.
A board’s risk tolerance reflects its members’ financial backgrounds and their experience with past market declines. It is also shaped by loss aversion, meaning that a loss tends to feel larger than a gain of the same size. A member with an investment background and a member whose experience is in programs or fundraising may view the same quarterly decline differently. Risk tolerance belongs to the people responsible for oversight, so it can change as board and committee members rotate, even if the organization’s finances do not. When evaluating risk tolerance, board members need to consider their risk tolerance as it relates to the organization’s reserves and not their own personal finances.
Risk tolerance belongs to the people responsible for oversight, so it can change as board and committee members rotate, even if the organization’s finances do not.
How to Determine Your Board’s Risk Tolerance
Your board’s risk tolerance is typically determined through a risk tolerance survey completed by each committee or board member, followed by a discussion of where the answers differ. This survey gives each member’s view equal weight before discussion begins, rather than letting the conversation follow whoever speaks first or has the most investment experience. At Raffa, we include this survey in our investment policy development process to gauge the committee’s or board’s willingness to endure market losses as it relates to the organization’s reserves.
When Board Members Disagree About Risk Tolerance
When board members disagree about risk tolerance, the goal is generally a shared position that reflects the full group’s input and stays within what the organization can afford. The survey results show how far apart members are, and the capacity assessment grounds the discussion in the organization’s financial position rather than individual opinions. Those facts can also show when a disagreement is really about capacity rather than tolerance, such as a concern that the reserve may be needed sooner than planned. Documenting how the committee reached its position can help future members understand the reasoning after the members who set it have rotated off.
What If Risk Tolerance and Risk Capacity Do Not Match?
When risk tolerance and risk capacity do not match, the portfolio for each pool is generally built to whichever supports less risk. This can help the organization avoid both a loss it cannot afford and a strategy the board may abandon during a decline. Recording the gap makes it easier to revisit as the organization’s finances change or board and committee members rotate.
When Risk Tolerance Is Higher Than Risk Capacity
When risk tolerance is higher than risk capacity, the nonprofit board may be comfortable with a decline the organization cannot afford, and capacity generally sets the limit. The board’s comfort with market declines does not change the organization’s finances. If the board wants a long-term pool to carry more risk than its capacity allows today, building capacity first, for example by growing the operating or emergency reserve, is one way to close the gap over time.
When Risk Capacity Is Higher Than Risk Tolerance
When risk capacity is higher than risk tolerance, the organization could afford more risk than the board is willing to accept, and the portfolio is generally built to the board’s risk tolerance. The right strategy for a charitable nonprofit or an association is generally one its board can stay with as markets shift and committee members change, even if another allocation offers a higher expected return. A strategy the committee would abandon during a decline can lead to selling after prices have fallen, which locks in the decline and gives up the chance to benefit if markets recover. Over time, education about how each pool is invested and why may help a committee accept more of the risk its capacity allows.
The right strategy for a charitable nonprofit or an association is generally one its board can stay with as markets shift and committee members change, even if another allocation offers a higher expected return.
How Reserve and Investment Policies Reflect Risk Tolerance and Risk Capacity
Reserve policies and investment policies typically reflect risk capacity and risk tolerance pool by pool, but in different ways. In the reserve policy, capacity guides which pools to hold, what each is for, and how much each should hold. In the Investment Policy Statement, capacity carries into each pool’s cash flow expectations and time horizon, while tolerance sets each pool’s risk level, asset allocation ranges, and eligible investments. Our article on what an investment policy should include offers greater detail on these IPS sections and how they connect to the reserve policy.
How Risk Capacity Shapes the Reserve Policy and IPS
Risk capacity helps shape both the reserve policy and the IPS, though neither typically has a section devoted to it. Assessing capacity shows how much money the organization may need and when, such as to sustain operations through a revenue shortfall or to fund planned projects. Those needs guide the reserve policy’s decisions about which pools to hold, what each is for, and how much each should hold, as our sample reserve policy shows. The IPS then reflects those decisions in each pool’s cash flow expectations and time horizon, such as a statement that a strategic reserve is not expected to be drawn on for seven years or more. With nearer-term needs covered by other pools, a long-term pool generally has more capacity to take investment risk.
How Risk Tolerance Is Reflected in an IPS
Risk tolerance is reflected in an IPS through each pool’s risk level, its asset allocation ranges, and the investments it is permitted to hold. In our sample investment policy statement template, it shows up in three elements:
- A risk level. Each pool is classified, for example as conservative, moderately conservative, or moderate, at a level both its capacity and the board’s tolerance support, often with a brief explanation drawn from its objectives, time horizon, and cash flow needs.
- Allocation ranges. For pools that hold both stocks and bonds, minimum, target, and maximum allocations for each asset class put the risk level into practice and give the committee a defined range to monitor.
- Eligible investments and limits. Because investments within the same asset class can carry different levels of risk, the IPS also lists what each pool may hold and sets limits, such as the average maturity and credit quality of its bonds or the share held in any one issuer.
When Risk Tolerance Is Higher Than Risk Capacity
When risk tolerance is higher than risk capacity, the nonprofit board may be comfortable with a decline the organization cannot afford, and capacity generally sets the limit. The board’s comfort with market declines does not change the organization’s finances. If the board wants a long-term pool to carry more risk than its capacity allows today, building capacity first, for example by growing the operating or emergency reserve, is one way to close the gap over time.
When Risk Capacity Is Higher Than Risk Tolerance
When risk capacity is higher than risk tolerance, the organization could afford more risk than the board is willing to accept, and the portfolio is generally built to the board’s risk tolerance. The right strategy for a charitable nonprofit or an association is generally one its board can stay with as markets shift and committee members change, even if another allocation offers a higher expected return. A strategy the committee would abandon during a decline can lead to selling after prices have fallen, which locks in the decline and gives up the chance to benefit if markets recover. Over time, education about how each pool is invested and why may help a committee accept more of the risk its capacity allows.
Strengthening Your Reserve & Investment Policies
If your organization is looking for opportunities to strengthen your governance policies or update your reserve policy, consider checking out our governance policy resources. Our Sample Reserve Policy, Sample IPS, and Nonprofit and Association Governance Policy Guide can be accessed through the buttons below.
When Should a Board Reassess Risk Tolerance and Risk Capacity?
A board should generally reassess risk tolerance and risk capacity on a schedule, as part of the annual IPS review and after changes in leadership or finances, rather than in response to a single difficult quarter. Three events typically call for a fresh look:
- The annual IPS review. A review that confirms the existing position is still a documented decision and a record of the board fulfilling its fiduciary responsibility.
- Board or committee rotation. When new members join the board or finance committee, they can take the survey, and board orientation and education can explain the position the board recorded and why.
- Changes in the organization’s finances. A large gift, the loss of a major revenue source, a new draw from the portfolio, or a reserve-funded project that now has a start date can each raise or lower capacity.
After a significant market decline, it can be useful to compare how members responded with the risk tolerance the board recorded. If members pushed to move to cash or change the allocation during the decline, the portfolio may carry more risk than the board is comfortable with, and it may be worth re-evaluating the allocation.
How Raffa Can Help
At Raffa Investment Advisers, we serve as a fiduciary investment advisor for nonprofits and associations, most often in an OCIO capacity, managing the portfolio within the guidelines of your organization’s IPS, including rebalancing when allocations drift outside policy-defined ranges, while your board retains oversight. Our process for developing or reviewing an IPS includes an assessment of your organization’s capacity to take on investment risk, a review of how your reserves are structured, and a risk tolerance survey of your committee or board. From there, we recommend a risk level and allocation ranges for each reserve pool and document the reasoning, so future board and committee members can see how the policy was set.
Schedule a Meeting with Our Team of Advisors Experienced in Partnering with Nonprofits and Associations
Frequently Asked Questions: Risk Tolerance vs. Risk Capacity
Which Matters More, Risk Tolerance or Risk Capacity?
Neither risk tolerance nor risk capacity matters more on its own, because each sets a different limit. Capacity is the outer limit: a portfolio generally should not carry more risk than the organization can afford, however comfortable the board is with market declines. Within that limit, tolerance determines whether the board will stay with the strategy through a decline, so the portfolio for each pool is generally built to whichever of the two supports less risk.
What Is a Risk Tolerance Survey?
A risk tolerance survey is a questionnaire that each committee or board member completes to gauge their willingness to accept market declines in the portfolio. Comparing the responses shows where members agree and where perspectives differ before the committee records a position in the IPS. The survey informs the board’s decision; it does not produce a correct answer on its own.
Who Should Complete a Board Risk Tolerance Survey?
A board risk tolerance survey is generally completed by whoever approves the IPS, which is often the finance or investment committee, with the full board ratifying the result. Including the full board can be useful when the board is small or the reserves are large relative to the operating budget. Ultimately, who completes the survey is a decision each board should make based on its own situation and preferences.
Can a Nonprofit’s Risk Capacity Change Without a Board Decision?
A nonprofit’s risk capacity can change without any board decision, because it depends on facts about the organization. A large gift from a donor, the loss of a major funder, growth in operating reserves, or a new draw from the portfolio can raise or lower capacity while the board’s tolerance stays the same. Reviewing capacity alongside the IPS each year can help the policy keep pace with those changes.
Do Associations Assess Risk Tolerance and Risk Capacity Differently?
Associations generally assess risk tolerance and risk capacity the same way as other nonprofits. The differences tend to come from revenue and leadership: dues and meeting revenue can concentrate income in a few sources and months of the year, and volunteer officers such as the treasurer and finance committee chair may change each year, which can make it worth revisiting the risk tolerance survey more often.
About the Author
Mark Murphy, CFA
Chief Investment Officer
Mark Murphy, CFA, is Chief Investment Officer at Raffa Investment Advisers and has more than 15 years of direct experience serving as an OCIO and lead portfolio manager for nonprofit organizations and membership associations. As Chief Investment Officer, Mark works closely with investment committees and staff to implement policy-driven investment programs designed to balance liquidity needs, risk management, and long-term financial sustainability. Mark is an active participant in the nonprofit and association community and has spoken on governance, fiduciary oversight, and nonprofit investing for organizations including the Greater Washington Society of CPAs, the AICPA, BoardSource, and the American Society of Association Executives.
Disclosures:
Portions of this article were drafted with the assistance of AI tools and reviewed by Raffa Investment Advisers staff for accuracy and compliance.
Raffa Investment Advisers is a registered investment adviser with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training.
All investments involve risk, including the possible loss of principal. Past performance is not indicative of future results.
Any forward-looking statements are based on current expectations and are subject to uncertainties.
This article is for informational purposes only and should not be construed as personalized investment advice.